Lithium (LC2701): Will Fear of Weak EVs Keep Prices Below 100,000?
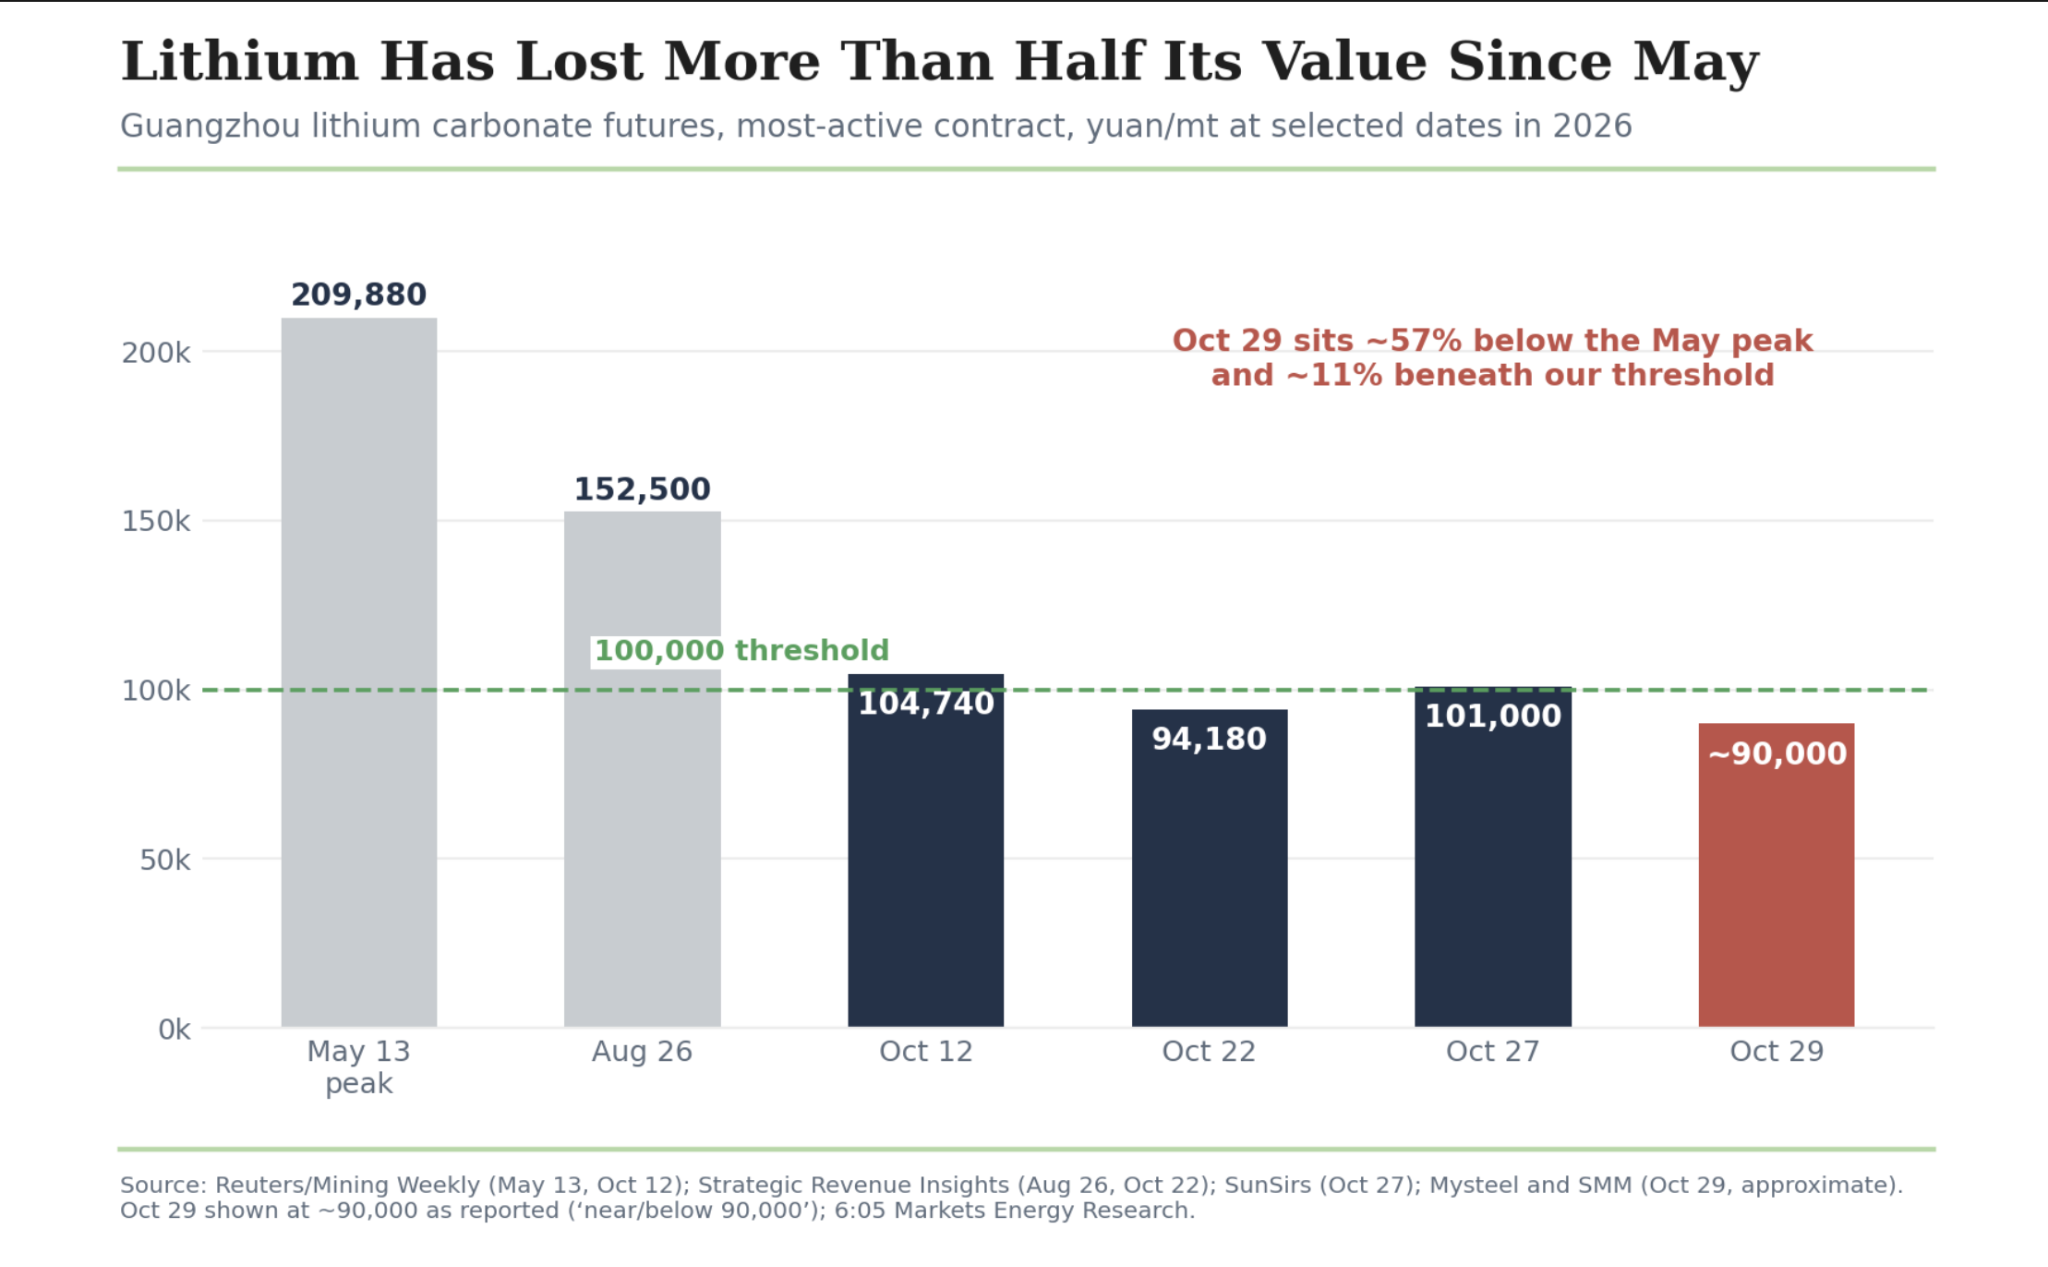
We expect LC2701 (Lithium Carbonate futures contracts, traded on the Guangzhou Futures Exchange) to settle above 100,000 yuan/mt on December 31, and Benchmark to report November global EV sales above the 2.0 million recorded a year earlier. Lithium has fallen by more than half from its 33-month high of 209,880 yuan on May 13, as worries about 2027 demand built up.
Executive Summary
We expect LC2701 (Lithium Carbonate futures contracts, traded on the Guangzhou Futures Exchange) to settle above 100,000 yuan/mt on December 31, and Benchmark to report November global EV sales above the 2.0 million recorded a year earlier. Lithium has fallen by more than half from its 33-month high of 209,880 yuan on May 13, as worries about 2027 demand built up. On October 29, the most-traded contract fell below 90,000 yuan/mt, a new year-to-date low, as the market absorbed expectations of an earlier-than-expected restart of the Jianxiawo mine. The sell-off, however, rests mostly on expectation rather than today’s consumption. For instance, an analysis of Goldman forecasts found that the decline reflects anticipated oversupply rather than an existing surplus. EV demand is uneven but not broken. Europe reached 0.6 million in September, up 39%, while China fell 18%. We are not forecasting a return to May’s peak. With prices now roughly 11% below our threshold, the lithium leg is clearly the more precarious half of the call.
Key Numbers
LC2701, as of Oct. 27 | Our threshold | Global EV sales in November 2025, the year-ago base | Resolution date |
|---|---|---|---|
98,500 yuan/mt | 100,000 yuan/mt | 2.0M | DEC. 31, 2026 |
Sources: Mining Weekly/Reuters, Oct. 12, 2026; Shanghai Metals Market (SMM), Oct. 29, 2026; Benchmark Mineral Intelligence (Sept. 2026 and Nov. 2025 EV reports); 6:05 Markets estimates.
The Price Hurdle
The lithium aspect of this prediction asks for relatively little, as a roughly 1.5% climb from 98,500 yuan/mt to 100,000 yuan/mt is well within lithium’s realm of possibility. Lithium has proven to have the volatility necessary to make that climb, falling 11.8% in a single session on Oct. 12. Additionally, 100,000 yuan/mt represents the midpoint of the 90,000–110,000 yuan/mt range expected in the Oct. 22 report.
The EV aspect needs sales above the 2.0 million recorded in November 2025. September 2026 was 2.15 million, 7.5% above that base, but was down about 2% from September 2025. Last year’s September-to-November drop was about 9%, which would imply 1.96 million if a similar drop occurs this year. The swing factor this year was North America, where September fell 44% against a pre-credit-expiry rush. If that drag (roughly 100,000 units) fades, November lands near 2.06 million, or +3%. Each 100,000 units moves the result about 5 points.
What’s Driving Lithium
Three forces explain the collapse, and only one of them is about actual supply and demand. The first is expected new supply. CATL’s Jianxiawo mine restarted its environmental impact review on October 8, and major Australian mines, including Bald Hill and Finniss, have resumed production, while Goldman forecasts global lithium supply will rise a staggering 32% next year.
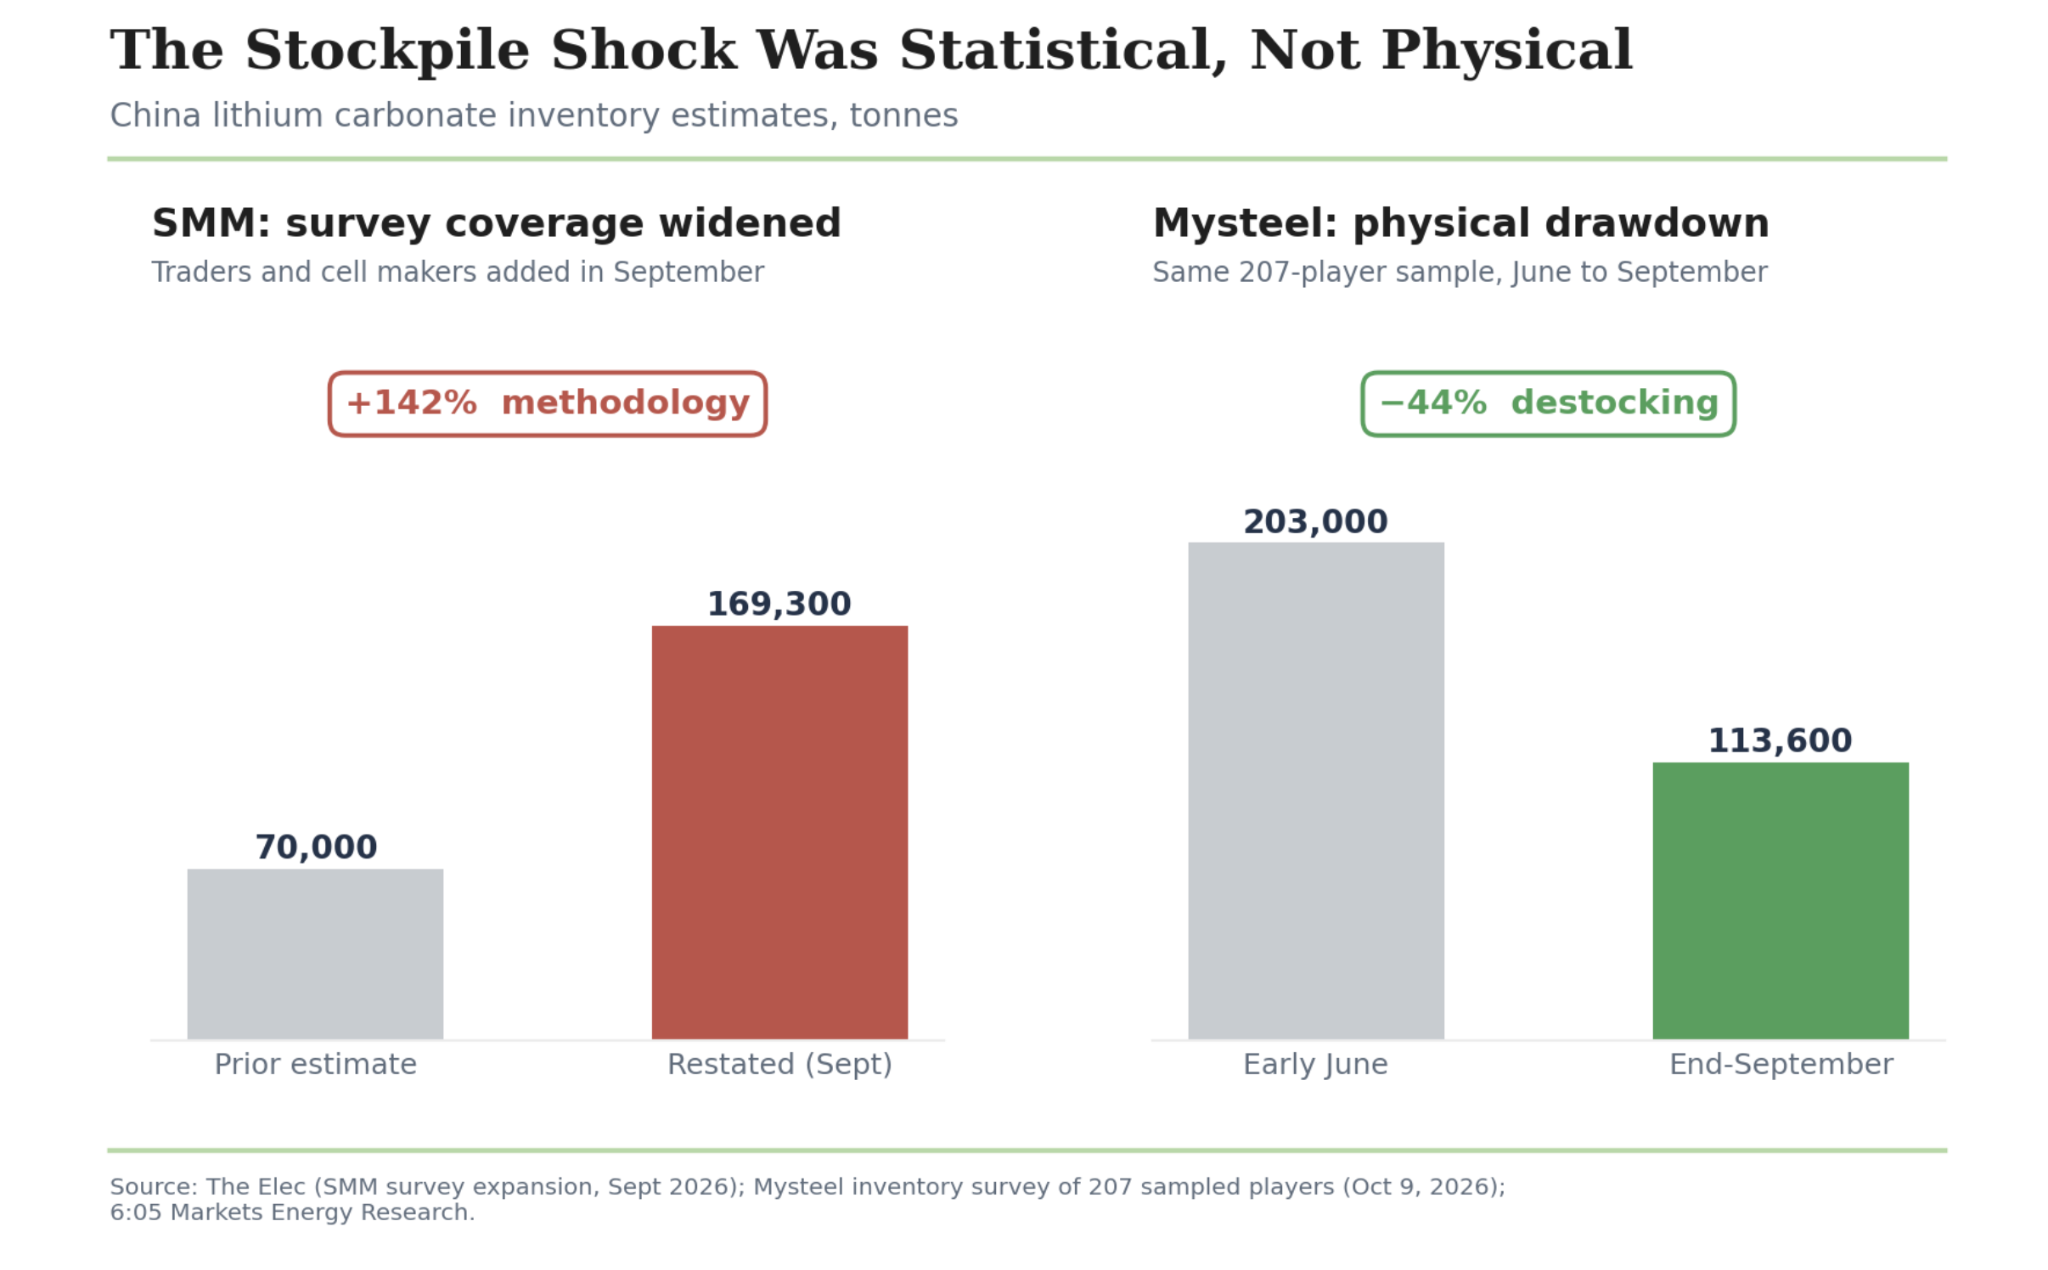
The second is a statistical artefact rather than a real glut. SMM widened its inventory survey in September to include traders and cell makers, lifting estimated stocks from about 70,000 to 169,300 tonnes; the increase reflected previously uncounted inventory, not a sudden build. Yet it prompted bullish futures holders to unwind. Physical stocks are actually falling. Mysteel’s 207-player survey shows inventories drawing down from 203,000 tonnes in early June to 113,600 at end-September, a roughly 44% decline. Downstream production is also rising: LFP output reached 603,200 tonnes in September and is expected to climb to 625,000 in October, while October carbonate production is projected to rise just 1.1% to 115,900 tonnes.
The third is positioning, which amplifies the other two. On Oct. 14, the 20 largest LC2701 holders were net short by about 30,000 contracts. Because futures now set the price of about 95% of commercial carbonate transactions, sentiment can easily overwhelm fundamentals.
EV Demand
As of September, global EV sales reached 15.5 million year to date, a mere 3% increase YoY. This number, however, masks a stark regional divide: China, the largest market by far, is down 13% on the year and fell 18% in September alone. Europe, on the other hand, set a monthly record with 600,000 units sold in September. This is relevant because, despite Europe’s good September this year, the same story was seen last year, so beating YoY figures is a harder endeavor. China was stagnant last September, but due to the sharp decline it sustained this September, it is also unlikely to beat YoY figures. There is also the matter of policy risk. The EU’s ban on Chinese EV imports still hasn’t gone through, and China’s 2% battery consumption tax will rise to 4% in 2027. Although North America has a more plausible chance of beating YoY comparisons, this doesn’t necessarily signal that EV demand is turning at this point.
Storage and Investment Reaction
Global BESS shipments rose a whopping 94% YoY over the first 8 months of 2026. Additionally, BNEF forecasts 2026 additions of 188 GW/535 GWh, an increase of 45%. However, BNEF’s 2027 projection of 209 GW/638 GWh suggests approximately 11% growth in GW and 19% growth in GWh, implying that storage will not be used to fill the EV gap. The slump has already been priced into equities: Albemarle went from $126.28 on September 4 to $92.54 on October 22, a 22% drawdown consistent with a market-wide move. The next test will be the company’s November 4 results. Because realized prices lag the index, guidance on volumes and the $400m cost-savings target will matter more than the $2.39 consensus EPS.
Scenarios and Expected Outcomes
Each scenario looks at whether LC2701 settles above or below 100,000 and how November sales will compare to last year’s 2.0M. The scenarios differ largely due to how much of the EV fear is realized (China, the EU cap) and whether new supply and traders’ bets push the price up or down.
Scenario | LC2701, Dec 31 | Nov global EV sales vs 2.0M | Driver |
|---|---|---|---|
| Bear | Below 100,000 | Down year on year | China’s decline widens, EU cap approved, shorts press |
| Base (our call) | 100,000-110,000 | 0% to +5% (2.0-2.1M) | Fear eases modestly, easier US comparisons |
| Bull | Above 110,000 | Above +5% | Short covering, tight Q4 destocking, strong Europe |
At 98,500, LC2701 needs to climb about 1.5% to clear 100,000. Our EV bridge estimates November EV sales near 2.06M, a rise of about 3%, and assumes North America stops falling year on year.
To examine what the shifts actually mean: on the EV side, every 100,000 cars moves November’s year-on-year figure by about 5 percentage points (100,000 ÷ 2.0M). China will be the largest driver of these scenarios, as it made up about 62% of last year’s global sales. This means each 1-point change in China’s year-on-year sales moves the global figure by about 0.6 points.
To get to our call: upstream stockpiles are at their lowest since April 2024 and the largest traders are net short, which sets up buying if sentiment turns. The lithium line is only 1.5% above the current price, and the contract fell 11.8% in a single day this month, so a gap that small is well within normal movement. Our EV estimate for November leans toward 3% year on year (about 2.06M, assuming North America stops falling year on year) because Benchmark expects comparisons to improve from Q4, North America’s year-ago base is weak, and Europe saw a monthly record in September. China’s decline is the main risk. We believe these results will move together, since both depend on the same EV-fear story. Considering those supportive macro variables, we believe LC2701 clearing 100,000 and EV sales above 2.0M is the most likely outcome.
What Would Change Our View?
Several developments would strengthen our conviction. In a nutshell, these include Albemarle guiding to firmer volumes on November 4, Benchmark’s October data in mid-November showing China’s decline narrowing from 18%, and continued destocking. On inventories, Mysteel sees inventory days possibly falling to around 15 in November, a yearly low. Short covering into a tighter spot market would likely speed any rebound.
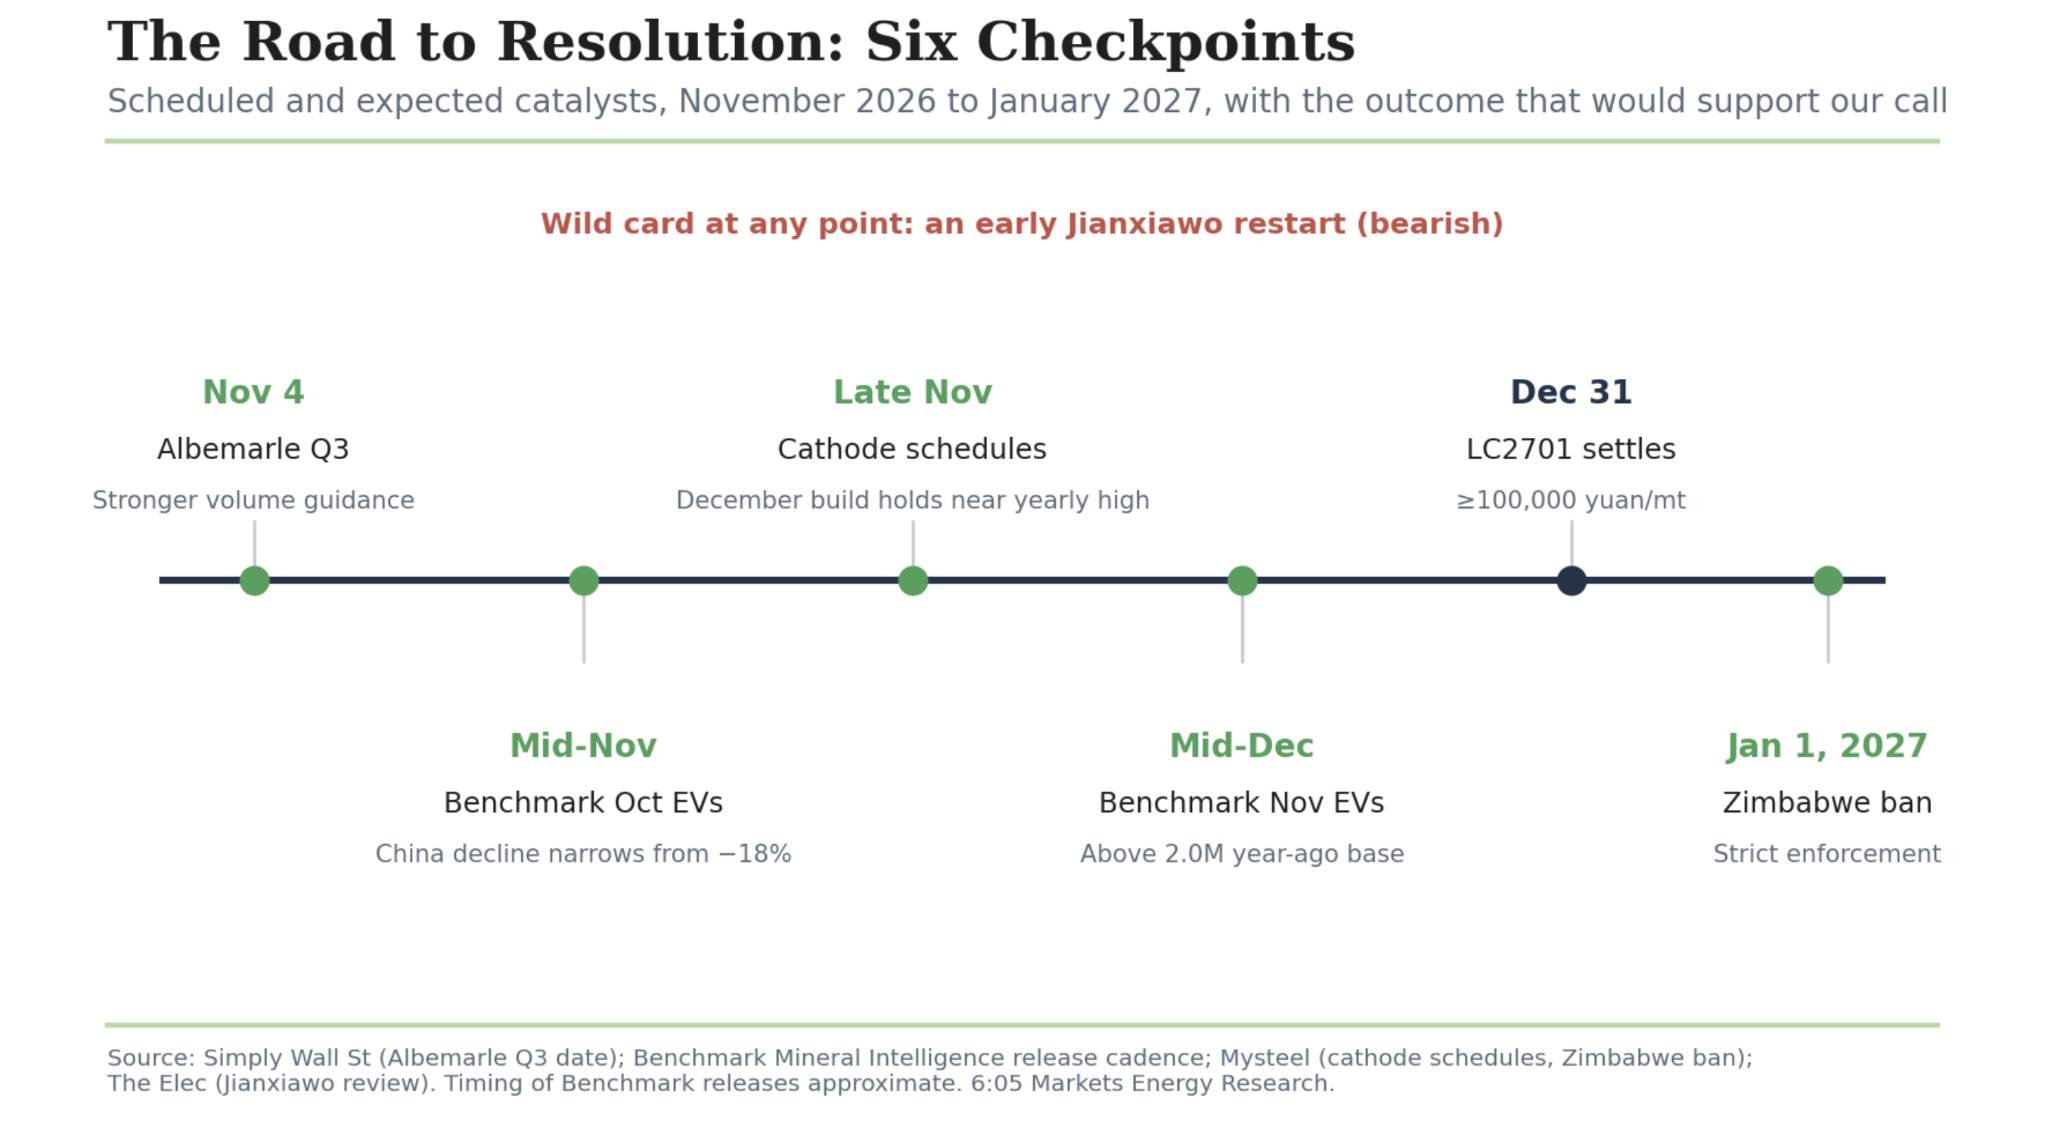
Conversely, we would reconsider if Jianxiawo restarts before year-end. If its review is completed this year, supply concerns could intensify, whereas a delay into next year would ease downward pressure. Weaker downstream demand would also undermine our view; Mysteel already notes that November cathode production scheduling will likely show a monthly reduction. Member-state approval of the EU hybrid cap or a renewed inventory build would weigh on the call as well. Zimbabwe remains an unresolved swing factor: its concentrate export ban takes effect January 1, 2027, and could affect about 160,000 tonnes of LCE a year if strictly enforced.
Conclusion
To conclude, we expect LC2701 to settle above 100,000 yuan/mt on December 31 and Benchmark to report November EV sales above last year’s figure of 2.0 million. The EV leg appears to command more confidence at the moment, whereas the lithium leg is close to a coin flip, since single-day volatility could easily push the price to either side of the established threshold. Three checkpoints will show which way it breaks: Albemarle’s results on Nov. 4, Benchmark’s October EV data in mid-November, and its November figures in mid-December.
Guangzhou lithium carbonate futures contract LC2701 will settle at or above 100,000 yuan/mt on 31 December 2026.
Series Lithium carbonate futures LC2701 (GFEX), yuan/mt Entry 98500.00 Range between 100,000.00 and 110,000.00 By 31 Dec 2026 Written 27 Oct 2026
Resolves against the readings entered for LC2701 on the last observation on or before 31 Dec 2026. Not investment advice.
Data Sources
- Mining Weekly (Reuters) – “Chinese lithium prices tumble to nearly 10-month low on demand concerns,” Oct. 12, 2026. The 209,880 May 13 high, the 11.8% fall to 104,740, and the EU-China hybrid deal.
- Shanghai Metals Market (SMM) – “[SMM Analysis] Lithium carbonate prices fell sharply this week, with the pace of inventory destocking slowing,” Oct. 29, 2026. The 88,360 Oct. 29 close, spot at 96,100, inventory of 128,385 t, and the 80,000-105,000 range.
- The Elec – “Lithium Prices Slump on Oversupply Fears, Raising Battery Market Uncertainty,” Oct. 2026. The top-20 holder positions, the SMM survey change (70,000 to 169,300 t), the Jianxiawo review restart on Oct. 8, Bald Hill and Finniss restarts, Zimbabwe’s January 2027 requirement, and the Goldman, CITIC, Huatai and CICC forecasts.
- BigGo Finance – “China’s Lithium Carbonate Futures Plunge Nearly 12%, Breaching 110,000 Yuan as Institutions Warn of 2027 Oversupply,” Oct. 2026. Mysteel’s Q4 survey (inventory days, cell schedules) and Goldman’s Oct. 6 report.
- Strategic Revenue Insights – “Lithium Price Crash 2026: What Broke the Rally,” Oct. 2026. LFP cathode output (603,200 to 625,000 t) and China’s September carbonate imports.
- Fastmarkets – “Fastmarkets Monthly BRM Update 2026,” Oct. 2026. Upstream salt inventories at their lowest since April 2024.
- Benchmark Mineral Intelligence – “Global EV sales reach 2.15 million units in September 2026,” Oct. 2026. Year-to-date 15.5M, up 3%; September 2.15M, down 2%; Europe’s record; improving comparisons from Q4.
- Benchmark Mineral Intelligence / Rho Motion – “Global EV sales reach 18.5 million, growing 21% YTD in Nov 25,” Dec. 12, 2025. The 2.0M November 2025 base, Europe up 36%, and North America’s post-credit slump.
- EVDANCE – “Global EV Sales in September 2026 by Region,” Oct. 2026. China’s 8.1M year to date, down 13%, and its September fall. (secondary)
- Electrek – “Europe’s EV sales soar as North America drops 44% – here’s the catch,” Oct. 15, 2026. North America’s 44% drop and the credit-expiry comparison.
- Benchmark Mineral Intelligence – “Battery Cell Price Review Q3 2026,” Oct. 2026. China’s 2% battery consumption tax from Sept. 1 and the pause on new cell capacity approvals.
- BloombergNEF – “Energy Storage Growth Surge Goes Global: Three Things to Know,” Oct. 2026. Storage additions of 209 GW/638 GWh in 2027.
- Seeking Alpha – “Lithium Miners News For The Month Of October 2026,” Oct. 2026. BESS shipments up 94% year on year. (secondary)
- Rio Times – “Lithium Wrap: LIT Falls as Albemarle Leads Miners Lower,” Sept. 5, 2026, and “Lithium Fund Falls 3.99% as SQM Drops 3.54%,” Oct. 22, 2026. Albemarle at $126.28 and $92.54.
- Albemarle Corporation – “Albemarle Corporation to Release Third Quarter 2026 Earnings,” Oct. 2026. Results on Nov. 4, call on Nov. 5.
- Simply Wall St – “Earnings Preview Could Be A Big Test For Albemarle (ALB),” Oct. 2026, and Yahoo Finance – “What to Expect From Albemarle’s Q3 2026 Earnings Report,” Oct. 2026. The $400m cost-savings target and $2.39 consensus EPS.